"Trading Parameters" Guideline (revised)
(GPT)
“Trading Parameters” Guideline
dated 14 August 2026 Entry into force: 1 October 2026
I Purpose
1 Purpose and principle
This "Trading Parameters" Guideline sets out the implementing ordinances for the trading segments pursuant to Clause 10.4 Trading Rules.
II Trading Segments
2 Classification of markets and trading segments
The Exchange operates the following markets and trading segments: a) Equity market
A Blue Chip Shares; B Mid-/Small-Cap Shares; C Sparks Shares; D Global Depository Receipts; E Secondary Listing Shares; F Sponsored Foreign Shares; G Rights and Options; H Separate Trading Lines; I Separate Trading Lines Equity Securities listed abroad; b) Fund market
J Investment Funds; K Exchange Traded Funds (ETF); L Sponsored Funds; c) Bond market
M Bonds – CHF Swiss Confederation; N Bonds – CHF Swiss Pfandbriefe; O Bonds – CHF; P Bonds – Non CHF; d) Structured Products market
Q Structured Products; R Structured Products ETH (Extended Trading Hours);
e) Market for «Other Financial Products»
S Exchange Traded Products (ETP); f) Other trading segments and trading services
T ETF/ETP QOD Europe; U QOD CHF-Bonds. The Exchange shall assign the securities to the individual trading segments. The Exchange shall specify the provisions for the individual trading segments in the annexes to this Guideline.
Resolution of the Management Committee of the Exchange of 14 August 2026, in effect since 1 October 2026.
Annex A – Blue Chip Shares Shares included in the Swiss Leader Index® (SLI®) are traded in the Blue Chip Shares segment.
1 Trading periods and times
The trading periods and times shall be set as follows: a) pre-opening from 06:00 to 09:00 (CET); b) opening from 09:00 (CET) with random opening within 2 minutes; c) continuous trading from opening until 17:20 (CET); d) closing auction from 17:20 to 17:30 (CET) with random end within 2 minutes; e) Trading-At-Last (TAL) from the closing auction until the close of trading at 17:40 (CET); f) post-trading from close of trading at 17:40 (CET) until 22:00 (CET).
2 Market model, order types and trading services
The rules of the Central Limit Order Book market model shall apply for on-exchange, on-order-book trading. Normal orders, Iceberg orders, Retail orders, Auction Volume Discovery orders and Block orders are supported. The Routing Instructions "SWMB" and "SWMX" are supported. The SwissAtMid and Swiss EBBO trading services are supported. The maximum duration of the firm-up phases for indicative Block orders in SwissAtMid are determined as follows: a) the manual firm-up phase lasts 30 seconds maximum with random execution if the conditions for execution are met; b) the automatic firm-up phase lasts 460 milliseconds maximum with random execution if the conditions for execution are met. The performance score thresholds for indicative Block orders are determined as follows: a) the performance score threshold value per participant and security in SwissAtMid with regard to blocking is 65. b) the performance score threshold value per participant for all SwissAtMid securities with regard to blocking is 65. The Quote on Demand trading service is not supported. Self Match Prevention is supported.
3 Order values
The minimum order value for Iceberg Orders is CHF 10,000, or the equivalent amount for securities which are traded in a foreign trading currency. The price collar factor is generally 9. The maximum order value is: a) CHF 100,000,000, or the equivalent amount for securities which are traded in a foreign trading currency, for the Central Limit Order Book;
b) CHF 250,000,000, or the equivalent amount for securities which are traded in a foreign trading currency, for the trading service SwissAtMid; c) CHF 100,000,000, or the equivalent amount for securities which are traded in a foreign trading currency for the trading service Swiss EBBO. The Exchange publishes the minimum order size per security compared with normal market size for Block orders in SwissAtMid together with the static data. In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communicate such adjustments in a suitable manner.
4 Trading interruption
The Exchange shall extend the auction time at opening (Delayed Auction) once by 5 minutes if the calculated auction price differs by 5% or more from the reference price or if not all unlimited orders can be executed. Continuous trading shall be interrupted for 5 minutes if the potential subsequent price differs a) by 1.5% or more from the current reference price; b) by 1.5% or more from a reference price valid within 10 seconds (Avalanche Stop). The Exchange shall extend the auction time in the closing auction (Delayed Auction) once by 5 minutes if the calculated auction price differs by 5% or more from the reference price or if not all unlimited orders can be executed. The Exchange shall open trading after a trading interruption with a random end within 30 seconds. In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communicate such adjustments in a suitable manner.
5 Price steps
The price steps of Annex D “Trading” Directive shall apply to the Central Limit Order Book and the trading service Swiss EBBO. Securities are allocated to price steps on the basis of the average number of trades (ANT) on the Exchange. For the trading service SwissAtMid, the valid price step is 0.0001 regardless of the order price.
6 Market making and liquidity providers
6.1 Market making
The Exchange does not organise any market making.
6.2 Liquidity providers
The Exchange may define liquidity requirements and admit liquidity providers. Liquidity providers undertake to comply with the conditions set out in the "List of Charges under the Trading Rules".
7 Clearing and settlement
Trades are cleared and settled via a central counterparty. The provisions of Clause 17 Trading Rules shall apply.
The counterparty shall remain anonymous.
8 Deadline for reporting off-order-book trades
If a trade is executed on-exchange, off-order-book during continuous trading, the report shall be made immediately, but no later than 1 minute after the trade has been effected. Trade reports for trades carried out in connection with a delta-neutral hedge with respect to a derivative transaction must be reported within five minutes at the latest. The trades are to be flagged with the trade type “Derivative Hedge” (Annex B “Trading” Directive). Trades executed off-order-book outside of continuous trading shall be reported before the opening of trading on the next trading day at the latest.
9 Delayed publication of off-order-book trades
The Exchange may publish trades with the necessary minimum volume, depending on the average daily turnover, with a delay if the securities transaction is conducted between a participant trading on its own account (Principal) and a client of this participant. The participant may demand delayed publication from the Exchange. The provisions on delayed publication pursuant to Annex C of the "Trading" Directive otherwise apply.
Annex B – Mid-/Small-Cap Shares Including shares that are listed in the regulatory standard for Special Purpose Acquisition Companies (SPACs).
1 Trading periods and times
The trading periods and times shall be set as follows: a) pre-opening from 06:00 to 09:00 (CET); b) opening from 09:00 (CET) with random opening within 2 minutes; c) continuous trading from opening until 17:20 (CET); d) closing auction from 17:20 to 17:30 (CET) with random end within 2 minutes; e) Trading-At-Last (TAL) from the closing auction until the close of trading at 17:40 (CET); f) post-trading from close of trading at 17:40 (CET) until 22:00 (CET).
2 Market model, order types and trading services
The rules of the Central Limit Order Book market model shall apply for on-exchange, on-order-book trading. Normal orders, Iceberg orders, Retail orders, Auction Volume Discovery orders and Block orders are supported. The Routing Instructions "SWMB" and "SWMX" are supported. The SwissAtMid and Swiss EBBO trading services are supported. The maximum duration of the firm-up phases for indicative Block orders in SwissAtMid is determined as follows: a) the manual firm-up phase lasts 30 seconds maximum with random execution if the execution conditions are met; b) the automatic firm-up phase lasts 460 milliseconds maximum with random execution if the execution conditions are met. The performance score thresholds for indicative Block orders are determined as follows: a) the performance score threshold value per participant and security in SwissAtMid with regard to blocking is 65. b) the performance score threshold value per participant for all SwissAtMid securities with regard to blocking is 65. The Quote on Demand trading service is not supported. Self Match Prevention is supported.
3 Order values
The minimum order value for Iceberg Orders is CHF 10,000, or the equivalent amount for securities which are traded in a foreign trading currency. The price collar factor is generally 9. The maximum order value is: a) CHF 50,000,000, or the equivalent amount for securities which are traded in a foreign trading currency, for the Central Limit Order Book;
b) CHF 250,000,000, or the equivalent amount for securities which are traded in a foreign trading currency, for the trading service SwissAtMid; c) CHF 50,000,000, or the equivalent amount for securities which are traded in a foreign trading currency for the trading service Swiss EBBO. The Exchange publishes the minimum order size per security compared with normal market size for Block orders in SwissAtMid together with the static data. In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communicate such adjustments in a suitable manner.
4 Trading interruption
The Exchange shall extend the auction time at opening (Delayed Auction) once by 15 minutes if the calculated auction price differs by 2% or more from the reference price or if not all unlimited orders can be executed. Continuous trading shall be interrupted for 15 minutes if the potential subsequent price differs a) by 2% or more from the current reference price; or b) by 2% or more from a reference price valid within 10 seconds (Avalanche Stop). The Exchange shall extend the auction time in the closing auction (Delayed Auction) once by 5 minutes if the calculated auction price differs by 2% or more from the reference price or if not all unlimited orders can be executed. For securities of the Swiss Market Index Mid (SMIM®), the delay in the opening or the trading interruption shall be 5 minutes and the bandwidth shall be 2% or more in accordance with letters a and b above. The extension of the closing auction shall be 5 minutes and the bandwidth shall be 2%. For volatile securities, the delay in the opening or the trading interruption shall be 5 minutes and the bandwidth shall be 10% or more in accordance with letters a and b above. The extension of the closing auction shall be 5 minutes and the bandwidth shall be 10%. The allocation of securities into the category of volatile securities is carried out by market control, taking into account the relevant market conditions such as liquidity and trading range. The Exchange shall open trading after a trading interruption with a random end within 30 seconds. In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communicate such adjustments in a suitable manner.
5 Price steps
The price steps of Annex D “Trading” Directive shall apply to the Central Limit Order Book and the trading service Swiss EBBO. Securities are allocated to price steps on the basis of the average number of trades (ANT) on the Exchange. For the trading service SwissAtMid, the valid price step is 0.0001 regardless of the order price.
6 Market making and liquidity providers
6.1 Market making
The Exchange does not organise any market making.
6.2 Liquidity providers
The Exchange may define liquidity requirements and admit liquidity providers. Liquidity providers undertake to comply with the conditions set out in the "List of Charges under the Trading Rules".
7 Clearing and settlement
Trades are cleared and settled via a central counterparty. The provisions of Clause 17 Trading Rules shall apply. The provisions of Clause 16 Trading Rules apply to trades in securities in the regulatory standard for Special Purpose Acquisition Companies (SPACs) that cannot be cleared and settled via a central counterparty. The counterparty shall remain anonymous.
8 Deadline for reporting off-order-book trades
If a trade is executed on-exchange, off-order-book during continuous trading, the report shall be made immediately, but no later than 1 minute after the trade has been effected. Trade reports for trades carried out in connection with a delta-neutral hedge with respect to a derivative transaction must be reported within five minutes at the latest. The trades are to be flagged with the trade type “Derivative Hedge” (Annex B “Trading” Directive). Trades executed off-order-book outside of continuous trading shall be reported before the opening of trading on the next trading day at the latest.
9 Delayed publication of off-order-book trades
The Exchange may publish trades with the necessary minimum volume, depending on the average daily turnover, with a delay if the securities transaction is conducted between a participant trading on its own account (Principal) and a client of this participant. The participant may demand delayed publication from the Exchange. The provisions on delayed publication pursuant to Annex C "Trading" Directive otherwise apply.
Annex C – Sparks Shares
1 Trading periods and times
The trading periods and times shall be set as follows: a) pre-opening from 06:00 to 09:00 (CET); b) opening from 09:00 (CET) with random opening within 2 minutes; c) continuous trading from opening until 17:20 (CET); d) closing auction from 17:20 to 17:30 (CET) with random close of trading within 2 minutes; e) Trading-At-Last (TAL) from the closing auction until the close of trading at 17:40 (CET); f) post-trading from close of trading at 17:40 (CET) until 22:00 (CET).
2 Market model, order types and trading services
The rules of the Central Limit Order Book market model shall apply for on-exchange, on-order-book trading. Normal orders, Iceberg orders, Retail orders, Auction Volume Discovery orders and Block orders are supported. The Routing Instructions “SWMB” and “SWMX” are supported. The SwissAtMid trading service is supported and the Swiss EBBO trading service is not supported. The maximum duration of the firm-up phases for indicative Block orders in SwissAtMid is determined as follows: a) the manual firm-up phase lasts a maximum of 30 seconds with execution at a random point if the conditions are met; b) the automatic firm-up phase lasts a maximum of 460 milliseconds with execution at a random point if the conditions are met. The performance score thresholds for indicative Block orders are determined as follows: a) the threshold value for the performance score per participant and security in SwissAtMid with regard to blocking is 65. b) the threshold value for the performance score per participant for all SwissAtMid securities with regard to blocking is 65. The Quote on Demand trading service is not supported. Self Match Prevention is supported.
3 Order values
The minimum order value for Iceberg Orders is CHF 10,000, or the equivalent amount for securities which are traded in a foreign trading currency. The price collar factor is generally 9. The maximum order value is: a) CHF 10,000,000, or the equivalent amount for securities which are traded in a foreign trading currency, for the Central Limit Order Book; b) CHF 10,000,000, or the equivalent amount for securities which are traded in a foreign trading currency, for the trading service SwissAtMid.
In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communicate such adjustments in a suitable manner.
4 Trading interruption
The Exchange shall extend the auction time at opening (Delayed Auction) once by 15 minutes if the calculated auction price differs by 5% or more from the reference price or if not all unlimited orders can be executed. Continuous trading shall be interrupted for 15 minutes if the potential subsequent price differs a) by 5% or more from the current reference price; or b) by 5% or more from a reference price valid within 10 seconds (Avalanche Stop). The Exchange shall extend the auction time in the closing auction (Delayed Auction) once by 5 minutes if the calculated auction price differs by 5% or more from the reference price or if not all unlimited orders can be executed. The Exchange shall open trading after a trading interruption with a random end within 30 seconds. In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communicate such adjustments in a suitable manner.
5 Price steps
The price steps of Annex D “Trading” Directive shall apply to the Central Limit Order Book. Securities are allocated to price steps on the basis of the average number of trades (ANT) on the Exchange. For the trading service SwissAtMid, the valid price step is 0.0001 regardless of the order price.
6 Market making and liquidity providers
6.1 Market making
The Exchange does not organise any market making.
6.2 Liquidity providers
The Exchange does not admit any liquidity providers.
7 Clearing and settlement
Trades are cleared and settled via a central counterparty. The provisions of Clause 17 Trading Rules shall apply. The counterparty shall remain anonymous.
8 Deadline for reporting off-order-book trades
If a trade is executed on-exchange, off-order-book during continuous trading, the report shall be made immediately, but no later than 1 minute after the trade has been effected. Trade reports for trades carried out in connection with a delta-neutral hedge with respect to a derivative transaction must be reported within five minutes at the latest. The trades are to be flagged with the trade type “Derivative Hedge” (Annex B “Trading” Directive).
Trades executed off-order-book outside of continuous trading shall be reported before the opening of trading on the next trading day at the latest.
9 Delayed publication of off-order-book trades
The Exchange may publish trades with the necessary minimum volume, depending on the average daily turnover, with a delay if the securities transaction is conducted between a participant trading on its own account (Principal) and a client of this participant. The participant may demand delayed publication from the Exchange. The provisions on delayed publication pursuant to Annex C of the “Trading” Directive otherwise apply.
Annex D – Global Depository Receipts Global Depository Receipts (GDRs) in the context of the Listing Rules.
1 Trading periods and times
The trading periods and times shall be set as follows: a) pre-opening from 06:00 to 11:00 (CET); b) opening from 15:00 (CET) with random opening within 2 minutes; c) continuous trading from opening until 17:20 (CET); d) closing auction from 17:20 to 17:30 (CET) with random end within 2 minutes; e) Trading-At-Last (TAL) from the closing auction until the close of trading at 17:40 (CET); f) post-trading from close of trading at 17:40 (CET) until 22:00 (CET).
2 Market model, order types and trading services
The rules of the Central Limit Order Book market model shall apply for on-exchange, on-order-book trading. Normal orders, Iceberg orders, Retail orders, Auction Volume Discovery orders and Block orders are supported. The Routing Instructions "SWMB" and "SWMX" are supported. The SwissAtMid trading service is supported and the Swiss EBBO trading service is not supported. The maximum duration of the firm-up phases for indicative Block orders in SwissAtMid is determined as follows: a) the manual firm-up phase lasts 30 seconds maximum with random execution if the execution conditions are met; b) the automatic firm-up phase lasts 460 milliseconds maximum with random execution if the execution conditions are met. The performance score thresholds for indicative Block orders are determined as follows: a) the performance score threshold value per participant and security in SwissAtMid with regard to blocking is 65. b) the performance score threshold value per participant for all SwissAtMid securities with regard to blocking is 65. The Quote on Demand trading service is not supported. Self Match Prevention is supported.
3 Order values
The minimum order value for Iceberg Orders is CHF 10,000, or the equivalent amount for securities which are traded in a foreign trading currency. The price collar factor is generally 9. The maximum order value is: a) CHF 50,000,000, or the equivalent amount for securities which are traded in a foreign trading currency, for the Central Limit Order Book;
b) CHF 250,000,000, or the equivalent amount for securities which are traded in a foreign trading currency, for the trading service SwissAtMid. The Exchange publishes the minimum order size per security compared with normal market size for Block orders in SwissAtMid together with the static data. In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communicate such adjustments in a suitable manner.
4 Trading interruption
The Exchange shall extend the auction time at opening (Delayed Auction) once by 15 minutes if the calculated auction price differs by 2% or more from the reference price or if not all unlimited orders can be executed. Continuous trading shall be interrupted for 15 minutes if the potential subsequent price differs a) by 2% or more from the current reference price; or b) by 2% or more from a reference price valid within 10 seconds (Avalanche Stop). The Exchange shall extend the auction time in the closing auction (Delayed Auction) once by 5 minutes if the calculated auction price differs by 2% or more from the reference price or if not all unlimited orders can be executed. The Exchange shall open trading after a trading interruption with a random end within 30 seconds. In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communicate such adjustments in a suitable manner.
5 Price steps
The price steps of Annex D “Trading” Directive shall apply to the Central Limit Order Book. Securities are allocated to price steps on the basis of the average number of trades (ANT) on the Exchange. For the trading service SwissAtMid, the valid price step is 0.0001 regardless of the order price.
6 Market making and liquidity providers
6.1 Market making
The Exchange does not organise any market making.
6.2 Liquidity providers
The Exchange does not admit any liquidity providers.
7 Clearing and settlement
Trades are cleared and settled via a central counterparty. The provisions of Clause 17 Trading Rules shall apply. The counterparty shall remain anonymous.
8 Deadline for reporting off-order-book trades
If a trade is executed on-exchange, off-order-book during continuous trading, the report shall be made immediately, but no later than 1 minute after the trade has been effected.
Trade reports for trades carried out in connection with a delta-neutral hedge with respect to a derivative transaction must be reported within five minutes at the latest. The trades are to be flagged with the trade type “Derivative Hedge” (Annex B “Trading” Directive). Trades executed off-order-book outside of continuous trading shall be reported before the opening of trading on the next trading day at the latest.
9 Delayed publication of off-order-book trades
The Exchange may publish trades with the necessary minimum volume, depending on the average daily turnover, with a delay if the securities transaction is conducted between a participant trading on its own account (Principal) and a client of this participant. The participant may demand delayed publication from the Exchange. The provisions on delayed publication pursuant to Annex C "Trading" Directive otherwise apply.
Annex E – Secondary Listing Shares
1 Trading periods and times
The trading periods and times shall be set as follows: a) pre-opening from 06:00 to 09:00 (CET); b) opening from 09:00 (CET) with random opening within 2 minutes; c) continuous trading from opening until 17:20 (CET); d) closing auction from 17:20 to 17:30 (CET) with random close of trading within 2 minutes; e) post-trading from close of trading until 22:00 (CET).
2 Market model, order types and trading services
The rules of the Central Limit Order Book market model shall apply for on-exchange, on-order-book trading. Normal orders, Iceberg orders, Retail orders and Auction Volume Discovery orders are supported. The Routing Instructions "SWMB" and "SWMX" are not supported. The SwissAtMid and Swiss EBBO trading services are not supported. The Quote on Demand trading service is not supported. Self Match Prevention is not supported.
3 Order values
The minimum order value for Iceberg Orders is CHF 10,000, or the equivalent amount for securities which are traded in a foreign trading currency. The price collar factor is 9. The maximum order value is CHF 10,000,000, or the equivalent amount for securities which are traded in a foreign trading currency. In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communicate such adjustments in a suitable manner.
4 Trading interruption
The Exchange shall extend the auction time at opening (Delayed Auction) once by 5 minutes if the calculated auction price differs by 2% or more from the reference price or if not all unlimited orders can be executed. Continuous trading shall be interrupted for 5 minutes if the potential subsequent price differs a) by 2.0% or more from the current reference price; or b) by 2.0% or more from a reference price valid within 10 seconds (Avalanche Stop). The Exchange shall extend the auction time in the closing auction (Delayed Auction) once by 5 minutes if the calculated auction price differs by 2% or more from the reference price or if not all unlimited orders can be executed. For volatile securities, the delay in the opening or the trading interruption shall be 5 minutes and the bandwidth shall be 10% or more in accordance with letters a and b above. The extension of the closing auction shall be 5 minutes and the bandwidth shall be 10%.
The allocation of securities into the category of volatile securities is carried out by market control, taking into account the relevant market conditions such as liquidity and trading range. The Exchange shall open trading after a trading interruption with a random end within 30 seconds. In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communicate such adjustments in a suitable manner.
5 Price steps
The price steps laid down in Annex D of the "Trading" Directive apply. Equity securities that are listed or admitted to trading on a European Union (EU) trading venue and are also admitted to trading on SIX Swiss Exchange AG are allocated to price steps on the basis of the average number of trades (ANT), as calculated and published by the European Securities and Markets Authority (ESMA). For equity securities that are listed or admitted to trading outside a European Union (EU) trading venue and are also admitted to trading on SIX Swiss Exchange AG the price steps of Liquidity Band A of Annex D of the "Trading" Directive are applicable.
6 Market making and liquidity providers
6.1 Market making
The Exchange does not organise any market making.
6.2 Liquidity providers
The Exchange does not admit any liquidity providers.
7 Clearing and settlement
Trades are cleared and settled via a central counterparty. The provisions of Clause 17 Trading Rules shall apply. The counterparty shall remain anonymous.
8 Deadline for reporting off-order-book trades
If a trade is executed on-exchange, off-order-book during continuous trading, the report shall be made immediately, but no later than 1 minute after the trade has been effected. Trade reports for trades carried out in connection with a delta-neutral hedge with respect to a derivative transaction must be reported within five minutes at the latest. The trades are to be flagged with the trade type “Derivative Hedge” (Annex B “Trading” Directive). Trades executed off-order-book outside of continuous trading shall be reported before the opening of trading on the next trading day at the latest.
9 Delayed publication of off-order-book trades
The Exchange may publish trades with the necessary minimum volume, depending on the average daily turnover, with a delay if the securities transaction is conducted between a participant trading on its own account (Principal) and a client of this participant.
The average daily turnover for equity securities that are listed or admitted to trading at a European Union (EU) trading venue is calculated according to the turnover on the primary market, as published by ESMA. The average daily turnover for equity securities that are listed or admitted to trading outside a European Union (EU) trading venue is calculated according to the turnover on SIX Swiss Exchange AG. The participant may demand delayed publication from the Exchange. The provisions on delayed publication pursuant to Annex C "Trading" Directive otherwise apply.
Annex F – Sponsored Foreign Shares
1 Trading periods and times
The trading periods and times shall be set as follows: a) pre-opening from 06:00 to 09:00 (CET); b) opening from 09:00 (CET) with random opening within 2 minutes; c) continuous trading from opening until 17:20 (CET); d) closing auction from 17:20 to 17:30 (CET) with random close of trading within 2 minutes; e) post-trading from close of trading until 22:00 (CET).
2 Market model, order types and trading services
The rules of the Quote Driven Market market model shall apply for on-exchange, on-order-book trading. Normal orders, Iceberg orders, Retail orders and quotes are supported. The Routing Instructions "SWMB" and "SWMX" are not supported. The SwissAtMid and Swiss EBBO trading services are not supported. The Quote on Demand trading service is not supported. Self Match Prevention is supported.
3 Order values
The price collar factor is 9. The maximum order value is CHF 10,000,000, or the equivalent amount for securities which are traded in a foreign trading currency. In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communicate such adjustments in a suitable manner.
4 Trading interruption
The Exchange shall extend the auction time at opening (Delayed Auction) once by a maximum of 5 minutes if there is no quote in the order book at the time of possible execution or if not all unlimited orders can be executed. Continuous trading shall be interrupted if there is no quote in the order book at the time of possible execution. Trading shall be immediately resumed as soon as a quote is entered, but no later than after 5 minutes. The Exchange shall extend the auction time in the closing auction (Delayed Auction) once by a maximum of 5 minutes if there is no quote in the order book at the time of possible execution or if not all unlimited orders can be executed. The Exchange shall open trading after a trading interruption with a random end within 30 seconds. In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communicate such adjustments in a suitable manner.
5 Price steps
The price steps laid down in Annex D of the "Trading" Directive apply. Equity securities that are listed or admitted to trading on a European Union (EU) trading venue and are also admitted to trading on SIX Swiss Exchange AG are allocated to price steps on the basis of the average number of trades (ANT), as calculated and published by the European Securities and Markets Authority (ESMA). For equity securities that are listed or admitted to trading outside a European Union (EU) trading venue and are also admitted to trading on SIX Swiss Exchange AG, the price steps of Liquidity Band F of Annex D – Price Steps (Tick Size) of the Directive 3: Trading are applicable.
6 Market making and liquidity providers
6.1 Market making
The Exchange shall organise market making and admit market makers. The market maker contractually undertakes to meet the following requirements over 80% (on a monthly basis) of the official trading times: a) if trading on the domestic market has been opened, the market maker shall provide bid and ask prices with a maximum trading spread of 2.5%; or b) if trading on the domestic market has not been opened, the market maker shall provide bid and ask prices with a maximum trading spread of 5%. The minimum volume on both the bid and ask sides is CHF 15,000.
6.2 Liquidity providers
The Exchange does not admit any liquidity providers.
7 Clearing and settlement
Trades are cleared and settled via a central counterparty. The provisions of Clause 17 Trading Rules shall apply. The counterparty shall remain anonymous.
8 Deadline for reporting off-order-book trades
If a trade is executed on-exchange, off-order-book during continuous trading, the report shall be made immediately, but no later than 1 minute after the trade has been effected. Trade reports for trades carried out in connection with a delta-neutral hedge with respect to a derivative transaction must be reported within five minutes at the latest. The trades are to be flagged with the trade type “Derivative Hedge” (Annex B “Trading” Directive). Trades executed off-order-book outside of continuous trading shall be reported before the opening of trading on the next trading day at the latest.
9 Delayed publication of off-order-book trades
The Exchange may publish trades with the necessary minimum volume, depending on the average daily turnover, with a delay if the securities transaction is conducted between a participant trading on its own account (Principal) and a client of this participant.
The average daily turnover for equity securities that are listed or admitted to trading at a European Union (EU) trading venue is calculated according to the turnover on the primary market, as published by ESMA. The average daily turnover for equity securities that are listed or admitted to trading outside a European Union (EU) trading venue is calculated according to the turnover on SIX Swiss Exchange AG. The participant may demand delayed publication from the Exchange. The provisions on delayed publication pursuant to Annex C "Trading" Directive otherwise apply.
7 Clearing and settlement
On the first trading day, the transfer and payment of trades must occur two trading days after the trade itself (T+2) ("value date"). From the second trading day onwards, the transfer and payment of trades must occur one trading day after the trade itself (T+1). Trades are not cleared and settled via a central counterparty. The provisions of Clause 16 Trading Rules shall apply. The counterparty shall be disclosed.
8 Deadline for reporting off-order-book trades
If a trade is executed on-exchange, off-order-book during continuous trading, the report shall be made immediately, but no later than 1 minute after the trade has been effected. Trades executed off-order-book outside of continuous trading shall be reported before the opening of trading on the next trading day at the latest.
9 Delayed publication of off-order-book trades
The delayed publication function is not available.
7 Clearing and settlement
Trades in Separate Trading Lines that are associated with a buy back of own equity securities for the purpose of a capital reduction shall be settled manually. Trades in Separate Trading Lines in connection with a public tender offer for cash or with a public exchange offer shall not be cleared and settled via a central counterparty. The provisions of Clause 16 Trading Rules shall apply. The counterparty shall be disclosed.
8 Deadline for reporting off-order-book trades
If an on-exchange, off-order-book trade associated with a public tender offer for cash or with a public exchange offer is executed in Separate Trading Lines during continuous trading, the report shall be made immediately, but no later than 1 minute after the trade is effected. Trades executed off-order-book outside of continuous trading shall be reported before the opening of trading on the next trading day at the latest. Trades in Separate Trading Lines in connection with a buy back of own equity securities or the purpose of a capital reduction may not be executed off-order-book.
9 Delayed publication of off-order-book trades
The Exchange may publish trades with the necessary minimum volume, depending on the average daily turnover, with a delay if the securities transaction is conducted between a participant trading on its own account (Principal) and a client of this participant. The average daily turnover is calculated according to the turnover on the relevant primary trading line. The participant may demand delayed publication from the Exchange. The provisions on delayed publication pursuant to Annex C "Trading" Directive otherwise apply.
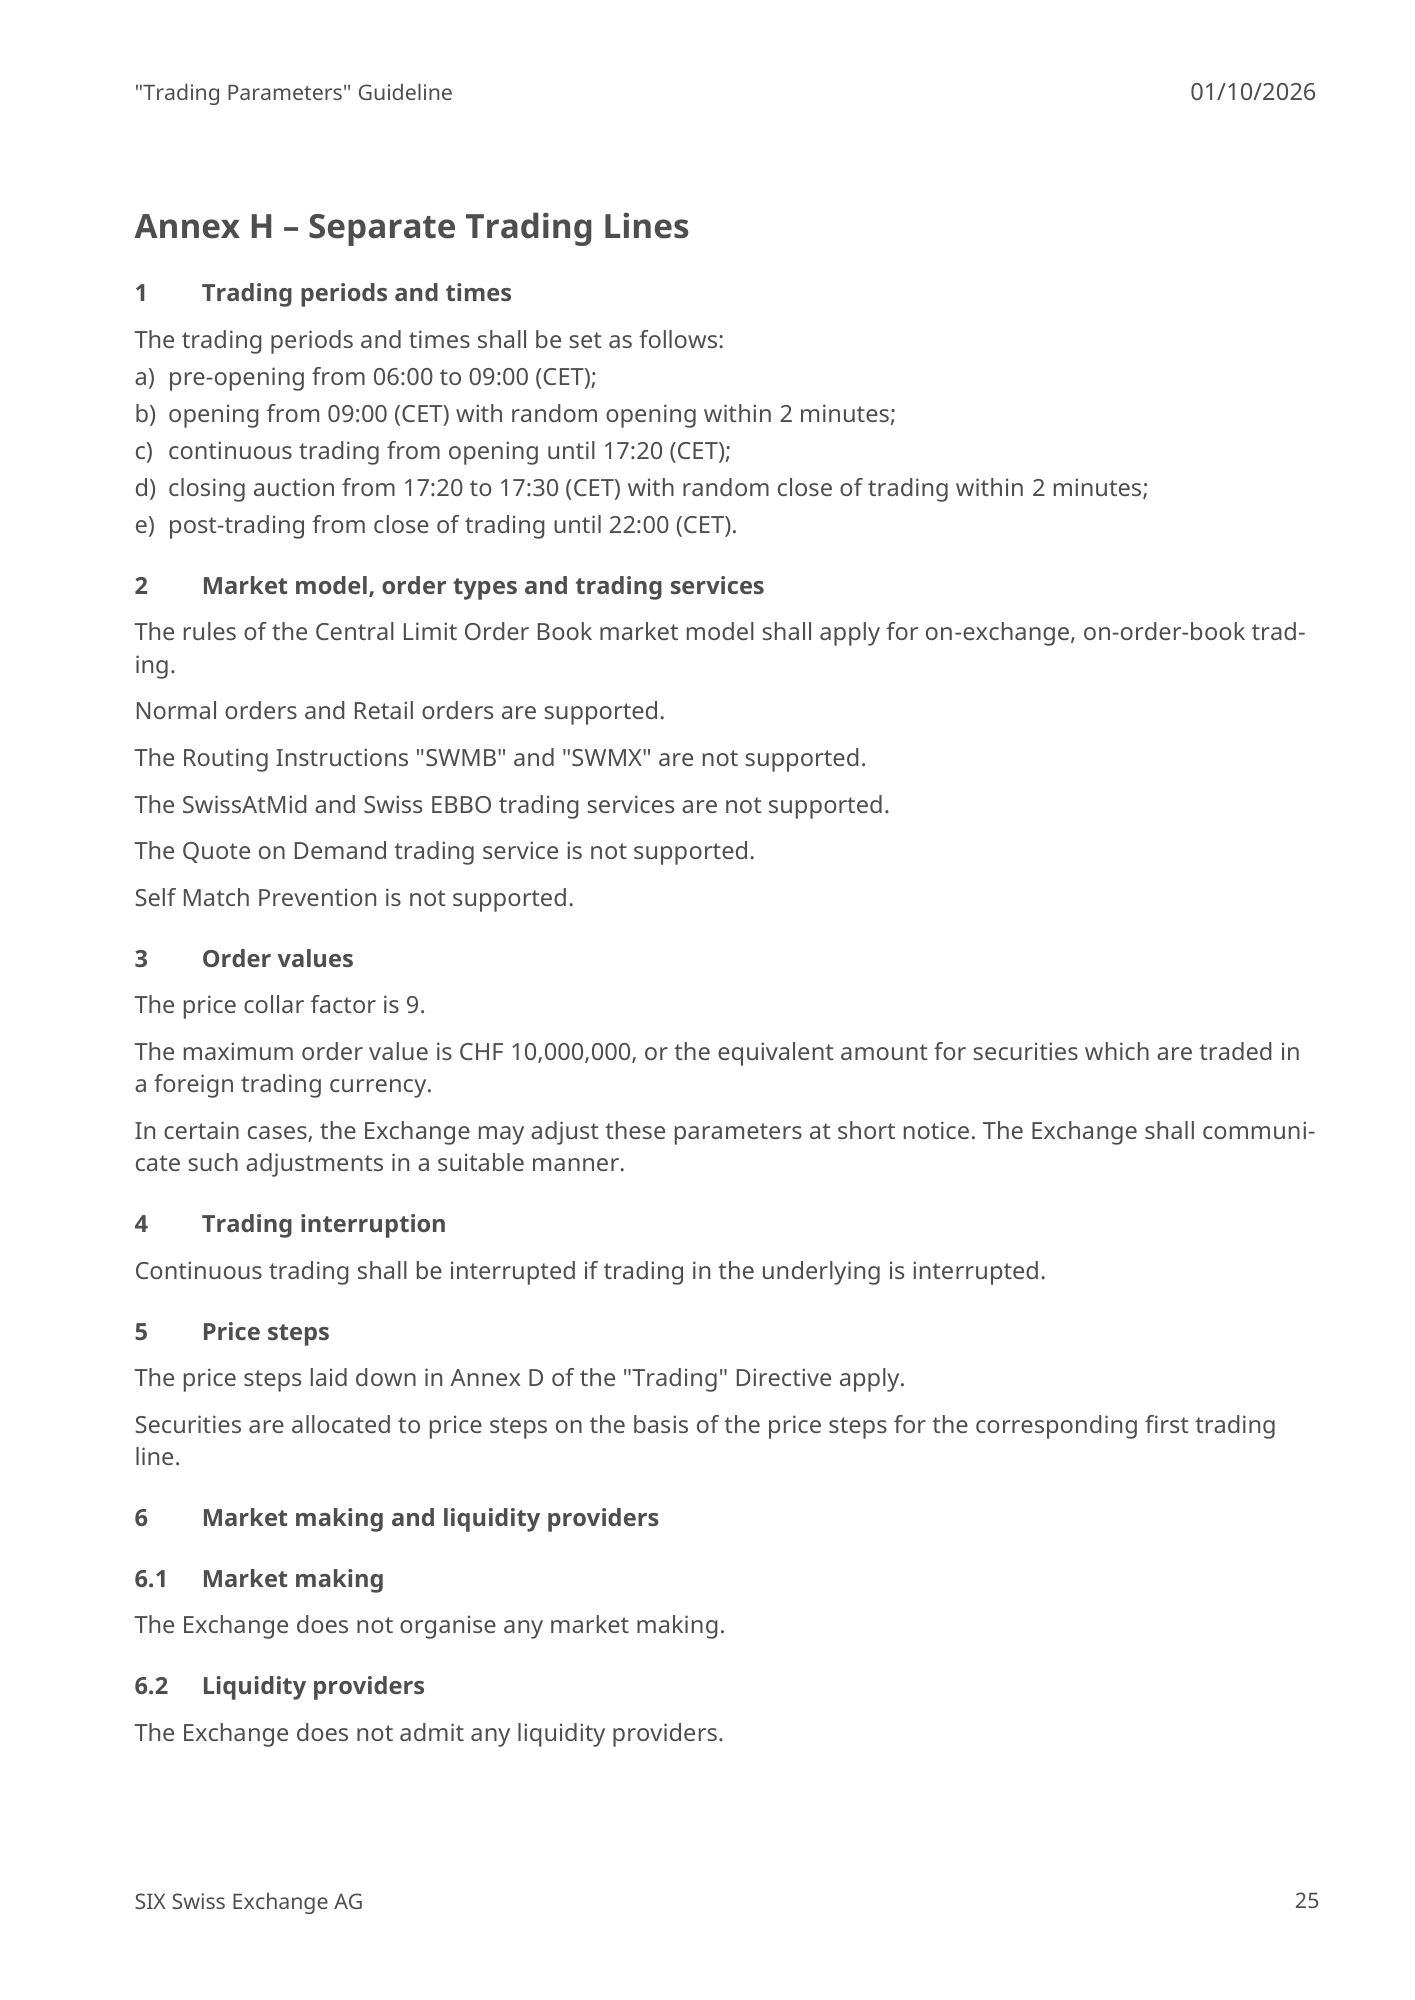
Annex I – Separate Trading Lines Equity Securities listed abroad Separate Trading Line for the purpose of buying back own equity securities of companies whose equity securities are listed on a stock exchange recognised by the Regulatory Board and which are deemed to be domiciled in Switzerland pursuant to the Federal Act on Withholding Tax (Withholding Tax Act, WTA), in accordance with Art. 3 para. 2 of the Rules for the Admission of Equity Securities and Exchange Traded Products to Trading (RAT).
1 Trading periods and times
The trading periods and times shall be set as follows: a) pre-opening from 06:00 to 09:00 (CET); b) opening from 09:00 (CET) with random opening within 2 minutes; c) continuous trading from opening until 21:45 (CET); d) close of trading without closing auction; e) post-trading from close of trading until 22:00 (CET).
2 Market model, order types and trading services
The rules of the Central Limit Order Book market model shall apply for on-exchange, on-order-book trading. Normal orders and Retail orders are supported. The Routing Instructions “SWMB” and “SWMX” are not supported. The SwissAtMid and Swiss EBBO trading services are not supported. The Quote on Demand trading service is not supported. Self Match Prevention is not supported.
3 Order values
The price collar factor is 9. The maximum order value is CHF 10,000,000, or the equivalent amount for securities which are traded in a foreign trading currency. In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communicate such adjustments in a suitable manner.
4 Trading interruption
Trading shall not be interrupted.
5 Price steps
Securities are allocated to price steps on the basis of the price steps for the corresponding first trading line on the stock exchange recognised by the Regulatory Board on which the securities are listed.
6 Market making and liquidity providers
6.1 Market making
The Exchange does not organise any market making.
6.2 Liquidity providers
The Exchange does not admit any liquidity providers.
7 Clearing and settlement
The transfer and payment of trades must occur three exchange days after the trade itself (T+3) “value date”. Trades in Separate Trading Lines that are associated with a buy back of own equity securities for the purpose of a capital reduction shall be settled manually. The counterparty shall be disclosed.
8 Deadline for reporting off-order-book trades
Trades in Separate Trading Lines in connection with a buy back of own equity securities for the purpose of a capital reduction may not be executed off-order-book.
9 Delayed publication of off-order-book trades
The delayed publication function is not available.
Annex J – Investment Funds
1 Trading periods and times
The trading periods and times shall be set as follows: a) pre-opening from 06:00 to 09:00 (CET); b) opening from 09:00 (CET) with random opening within 2 minutes; c) continuous trading from opening until 17:20 (CET); d) closing auction from 17:20 to 17:30 (CET) with random end within 2 minutes; e) Trading-At-Last (TAL) from the closing auction until the close of trading at 17:40 (CET); f) post-trading from close of trading at 17:40 (CET) until 22:00 (CET).
2 Market model, order types and trading services
The rules of the Central Limit Order Book market model shall apply for on-exchange, on-order-book trading. Normal orders, Iceberg orders, Retail orders, Auction Volume Discovery orders and Block orders are supported. The Routing Instructions "SWMB" and "SWMX" are supported. The SwissAtMid trading service is supported and the Swiss EBBO trading service is not supported. The maximum duration of the firm-up phases for indicative Block orders in SwissAtMid is determined as follows: a) the manual firm-up phase lasts a maximum of 30 seconds with execution at a random point if the conditions are met; b) the automatic firm-up phase lasts a maximum of 460 milliseconds with execution at a random point if the conditions are met. The performance score thresholds for indicative Block orders are determined as follows: a) the threshold value for the performance score per participant and security in SwissAtMid with regard to blocking is 65. b) the threshold value for the performance score per participant for all SwissAtMid securities with regard to blocking is 65. The Quote on Demand trading service is not supported. Self Match Prevention is supported.
3 Order values
The minimum order value for Iceberg Orders is CHF 10,000, or the equivalent amount for securities which are traded in a foreign trading currency. The price collar factor is generally 9. The maximum order value is: a) CHF 50,000,000, or the equivalent amount for securities which are traded in a foreign trading currency, for the Central Limit Order Book; b) CHF 50,000,000, or the equivalent amount for securities which are traded in a foreign trading currency, for the trading service SwissAtMid.
In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communicate such adjustments in a suitable manner.
4 Trading interruption
The Exchange shall extend the auction time at opening (Delayed Auction) once by 15 minutes if the calculated auction price differs by 2% or more from the reference price or if not all unlimited orders can be executed. Continuous trading shall be interrupted for 15 minutes if the potential subsequent price differs a) by 2% or more from the current reference price; or b) by 2% or more from a reference price valid within 10 seconds (Avalanche Stop). The Exchange shall extend the auction time in the closing auction (Delayed Auction) once by 5 minutes if the calculated auction price differs by 2% or more from the reference price or if not all unlimited orders can be executed. For volatile securities, the delay in the opening or the trading interruption shall be 5 minutes and the bandwidth shall be 10% or more in accordance with letters a and b above. The extension of the closing auction shall be 5 minutes and the bandwidth shall be 10%. The allocation of securities into the category of volatile securities is carried out by market control, taking into account the relevant market conditions such as liquidity and trading range. The Exchange shall open trading after a trading interruption with a random end within 30 seconds. In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communicate such adjustments in a suitable manner.
5 Price steps
The price steps laid down in Liquidity Band C Annex D of the “Trading” directive apply to the Central Limit Order Book. For the trading service SwissAtMid, the valid price step is 0.0001 regardless of the order price.
6 Market making and liquidity providers
6.1 Market making
The Exchange does not organise any market making.
6.2 Liquidity providers
The Exchange does not admit any liquidity providers.
7 Clearing and settlement
Trades are cleared and settled via a central counterparty. The provisions of Clause 17 Trading Rules shall apply. The counterparty shall be disclosed.
8 Deadline for reporting off-order-book trades
If a trade is executed on-exchange, off-order-book during continuous trading, the report shall be made immediately, but no later than 3 minutes after the trade has been effected.
Trades at a future net asset value are deemed to be effected in accordance with paragraph 1 as soon as the net asset value on which the trade is based is known. The trades are to be reported with the trade type “NAV Trade” (Annex B “Trading” directive). Trades executed off-order-book outside of continuous trading shall be reported before the opening of trading on the next trading day at the latest.
9 Delayed publication of off-order-book trades
The delayed publication function is not available.
Annex K – Exchange Traded Funds (ETF)
1 Trading periods and times
The trading times shall be set as follows: a) pre-opening from 06:00 to 09:00 (CET); b) opening from 09:00 (CET) with random opening within 2 minutes; c) continuous trading from opening until 17:30 (CET) (up to 17:00 (CET) in the case of ETFs on bonds of the Swiss Confederation); d) closing auction from 17:30 to 17:35 (CET) with random close of trading within 2 minutes (close of trading without closing auction for ETF on Bonds of the Swiss Confederation); e) post-trading from close of trading until 22:00 (CET).
2 Market model, order types and trading services
The rules of the Quote Driven Market market model shall apply for on-exchange, on-order-book trading. Normal orders, Iceberg orders, Retail orders and quotes are supported. The Routing Instructions "SWMB" and "SWMX" are not supported. The Quote on Demand trading service is supported. The default value for the maximum duration of the trading modes for Quote on Demand is determined as follows: a) “Discretion only” lasts 5 minutes maximum; b) “Auto-Execute or Cancel” lasts 1 second maximum with random execution if the conditions for execution are met; c) “Auto-Execute and Optional Discretion” lasts 1 second maximum with random execution if the conditions for execution are met and if no execution occurs, an additional 5 minutes maximum. The standard value for the minimum number of responding liquidity providers for automatic execution (“Auto-Execute”) is 1. The participant may individually select a maximum of 10 Quote on Demand registered liquidity providers for a quote request. The participant identification (Party ID) of the participant for quote requests is disclosed to the liquidity providers. The designation of the transaction type (buy/sell) of the quote requests is not disclosed to the liquidity providers. Self Match Prevention is supported for Quote Driven Market. Self Match Prevention is not supported for Quote on Demand.
3 Order values
The price collar factor is generally 9. The maximum order value is: a) CHF 10,000,000, or the equivalent amount for securities which are traded in a foreign trading currency for Quote Driven Market; b) CHF 250,000,000, or the equivalent amount for securities which are traded in a foreign trading currency for Quote on Demand. The price deviation of quote requests to the current price in the Quote Driven Market (QDM) is 10% or more.
In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communicate such adjustments in a suitable manner.
4 Trading interruption
The Exchange shall extend the auction time at opening (Delayed Auction) once by a maximum of 5 minutes if there is no quote in the order book at the time of possible execution or if not all unlimited orders can be executed. Continuous trading shall be interrupted if there is no quote in the order book at the time of possible execution. Trading shall be immediately resumed as soon as a quote is entered, but no later than after 5 minutes. The Exchange shall extend the auction time in the closing auction (Delayed Auction) once by a maximum of 2 minutes if there is no quote in the order book at the time of possible execution or if not all unlimited orders can be executed. The Exchange shall open trading after a trading interruption with a random end within 30 seconds. In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communicate such adjustments in a suitable manner.
5 Price steps
5.1 Quote Driven Market
The price steps laid down in Liquidity Band F of Annex D of the “Trading” Directive apply in principle to the Quote Driven Market. The valid price steps for securities in the money market products and fixed income investment category are defined as follows depending on the order price (details in trading currency):
From | To | Price steps | |
|---|---|---|---|
a) | 0.01 | 4.9999 | 0.0001 |
b) | 5 | 9.9998 | 0.0002 |
c) | 10 | 19.9995 | 0.0005 |
d) | 20 | 49.999 | 0.001 |
e) | 50 | 99.998 | 0.002 |
f) | 100 | 199.995 | 0.005 |
g) | 200 | 499.99 | 0.01 |
h) | 500 | 999.98 | 0.02 |
i) | 1,000 | 1,999.95 | 0.05 |
j) | 2,000 | 4,999.90 | 0.1 |
k) | 5,000 | 9,999.80 | 0.2 |
l) | 10,000 | 19,999.50 | 0.5 |
m) | 20,000 | 49,999 | 1 |
n) | 50,000 | and over | 2 |
The valid price steps for securities with a reference price of 100,000 or above in the relevant trading currency shall be 10.00 regardless of the order price and investment category.
5.2 Quote on Demand
For the trading service Quote on Demand, the valid price step is 0.0001 regardless of the order price. The valid price steps for securities with Japanese Yen (JPY) as their trading currency shall be 1.00 regardless of the order price.
6 Market making and liquidity providers
6.1 Quote Driven Market
6.1.1 Market making
The Exchange shall organise market making and admit market makers. The market maker contractually undertakes to meet the following requirements over 90% (on a monthly basis) of the official trading times:
6.1.1.1 ETF on share indices
a) If trading on the domestic market of at least 50% of underlyings has been opened, the market maker shall provide bid and ask prices which do not differ from the indicative NAV (net asset value) by more than 2% (+/- 1% on either side); or b) If trading on the domestic market of at least 50% of underlyings has not been opened, the market maker shall provide bid and ask prices with a maximum trading spread of 5%. The minimum volume on both the bid and ask sides is EUR 50,000.
6.1.1.2 ETF on fixed income indices
The maximum trading spread around the indicative iNAV (if available) shall be: a) for money market products: 0.1% (+/- 0.05% on either side of the iNAV, if available); b) for money market products not traded in the fund currency: 0.5% (+/- 0.25% on either side of the iNAV, if available); c) for government bonds, supranationals and similar bonds with a term of less than 3 years: 0.5% (+/- 0.25% on either side of the iNAV, if available); d) for government bonds, supranationals and similar bonds with a term of more than 3 years and for investment-grade corporate bonds: 1.0% (+/- 0.5% on either side of the iNAV, if available); e) for emerging market bonds and non-investment-grade corporate bonds: 2.0% (+/- 1.0% on either side of the iNAV, if available). The minimum volume on both the bid and ask sides is EUR 100,000.
6.1.1.3 ETF on commodities indices
a) If trading on the domestic market of at least 50% of underlyings has been opened, the market maker shall provide bid and ask prices which do not differ from the indicative NAV (net asset value) by more than 2% (+/- 1% on either side); or b) if trading on the domestic market of at least 50% of underlyings has not been opened, the market maker shall provide bid and ask prices with a maximum trading spread of 3%. The minimum volume on both the bid and ask sides is EUR 50,000.
6.1.1.4 ETF on collective capital investments indices
The maximum trading spread around the indicative iNAV (if available) shall be: a) for exchange-traded real estate funds: 2.0% (+/- 1.0% on either side of the iNAV, if available), if 50% of the collective capital investment falls into this investment category; b) for hedge fund indices: 2.0% (+/- 1.0% on either side of the iNAV, if available), if 50% of the collective capital investment falls into this investment category. The minimum volume on both the bid and ask sides is EUR 50,000.
6.1.2 Quote on Demand
The Exchange does not organise any market making.
6.2 Liquidity providers
6.2.1 Quote-Driven-Market
The Exchange does not admit any liquidity providers.
6.2.2 Quote on Demand
The Exchange may define liquidity requirements and admit liquidity providers. Liquidity providers undertake to comply with the conditions set out in the “List of Charges under the Trading Rules.
7 Clearing and settlement
Trades are cleared and settled via a central counterparty. The provisions of Clause 17 Trading Rules shall apply. The counterparty shall be disclosed.
8 Deadline for reporting off-order-book trades
If a trade is executed on-exchange, off-order-book during continuous trading, the report shall be made immediately, but no later than 3 minutes after the trade has been effected. Trades at a future net asset value are deemed to be effected in accordance with paragraph 1 as soon as the net asset value on which the trade is based is known. The trades are to be reported with the trade type “NAV Trade” (Annex B “Trading” directive). Trades executed off-order-book outside of continuous trading shall be reported before the opening of trading on the next trading day at the latest.
9 Delayed publication of trades
9.1 Trades in the Quote Driven Market and off-order-book
The delayed publication function is not available.
9.2 Trades in the Quote on Demand trade service
The Exchange may publish trades with the required minimum order size on a delayed basis compared with normal market size. The provisions on delayed publication pursuant to Clause 11.14 of the “Alternative Trading” directive apply.
Annex L – Sponsored Funds
1 Trading periods and times
The trading times shall be set as follows: a) pre-opening from 06:00 to 09:15 (CET); b) opening from 09:15 (CET) with random opening within 2 minutes; c) continuous trading from opening until 17:30 (CET); d) closing auction from 17:30 to 17:35 (CET) with random close of trading within 2 minutes; e) post-trading from close of trading until 22:00 (CET).
2 Market model, order types and trading services
The rules of the Quote Driven Market market model shall apply for on-exchange, on-order-book trading. Normal orders, Iceberg orders, Retail orders and quotes are supported. The Routing Instructions "SWMB" and "SWMX" are not supported. The SwissAtMid and Swiss EBBO trading services are not supported. The Quote on Demand trading service is not supported. Self Match Prevention is supported.
3 Order values
The price collar factor is 9. The maximum order value is CHF 10,000,000, or the equivalent amount for securities which are traded in a foreign trading currency. In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communicate such adjustments in a suitable manner.
4 Trading interruption
The Exchange shall extend the auction time at opening (Delayed Auction) once by a maximum of 5 minutes if there is no quote in the order book at the time of possible execution or if not all unlimited orders can be executed. Continuous trading shall be interrupted if there is no quote in the order book at the time of possible execution. Trading shall be immediately resumed as soon as a quote is entered, but no later than after 5 minutes. The Exchange shall extend the auction time in the closing auction (Delayed Auction) once by a maximum of 2 minutes if there is no quote in the order book at the time of possible execution or if not all unlimited orders can be executed. The Exchange shall open trading after a trading interruption with a random end within 30 seconds. In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communicate such adjustments in a suitable manner.
5 Price steps
The price steps laid down in Liquidity Band F of Annex D of the “Trading” Directive apply in principle.
The valid price steps for securities with a reference price of 100,000 or above in the relevant trading currency shall be 10.00 regardless of the order price and investment category.
6 Market making and liquidity providers
6.1 Market making
The Exchange shall organise market making and admit market makers. The market maker contractually undertakes to meet the following requirements over 90% (on a monthly basis) of the official trading times:
6.1.1 Sponsored Funds whose underlyings are primarily equities
a) If trading on the domestic market of at least 50% of underlyings has been opened, the market maker shall provide bid and ask prices with a maximum trading spread of 2%; or b) if trading on the domestic market of at least 50% of underlyings has not been opened, the market maker shall provide bid and ask prices with a maximum trading spread of 3%. The minimum volume on both the bid and ask sides is EUR 50,000.
6.1.2 Sponsored Funds whose underlyings are primarily fixed income instruments
The maximum trading spreads shall be as follows: a) for money market products: 0.1%; b) for money market products not traded in the fund currency: 0.5%; c) for government bonds, supranationals and similar bonds with a term of less than 3 years: 0.5%; d) for government bonds, supranationals and similar bonds with a term of more than 3 years and for investment-grade corporate bonds: 1.0%; e) for emerging market bonds and non-investment-grade corporate bonds: 2.0%; The minimum volume on both the bid and ask side is EUR 100,000.
6.1.3 Sponsored Funds whose underlyings are primarily commodities
a) If trading on the domestic market of at least 50% of underlyings has been opened, the market maker shall provide bid and ask prices with a maximum trading spread of 2%; or b) if trading on the domestic market of at least 50% of underlyings has not been opened, the market maker shall provide bid and ask prices with a maximum trading spread of 3%. The minimum volume on both the bid and ask sides is EUR 50,000.
6.2 Liquidity providers
The Exchange does not admit any liquidity providers.
7 Clearing and settlement
Trades are not cleared and settled via a central counterparty. The provisions of Clause 16 Trading Rules shall apply. The counterparty shall be disclosed.
8 Deadline for reporting off-order-book trades
If a trade is executed on-exchange, off-order-book during continuous trading, the report shall be made immediately, but no later than 3 minutes after the trade has been effected. Trades at a future net asset value are deemed to be effected in accordance with paragraph 1 as soon as the net asset value on which the trade is based is known. The trades are to be reported with the trade type “NAV Trade” (Annex B “Trading” directive). Trades executed off-order-book outside of continuous trading shall be reported before the opening of trading on the next trading day at the latest.
9 Delayed publication of off-order-book trades
The delayed publication function is not available.
Annex M – Bonds - CHF Swiss Confederation
1 Trading periods and times
The trading periods and times shall be set as follows: a) pre-opening from 06:00 to 08:30 (CET); b) opening from 08:30 (CET) with random opening within 2 minutes; c) continuous trading from opening until 17:00 (CET); d) close of trading without closing auction; e) post-trading from close of trading until 22:00 (CET).
2 Market model, order types and trading services
The rules of the Central Limit Order Book market model shall apply for on-exchange, on-order-book trading. Normal orders, Iceberg orders and quotes are supported. The Routing Instructions "SWMB" and "SWMX" are not supported. The SwissAtMid and Swiss EBBO trading services are not supported. The Quote on Demand trading service is supported pursuant to Annex U. Self Match Prevention is not supported.
3 Order values
The price collar factor is 9. The maximum order value is CHF 50,000,000, or the equivalent amount for securities which are traded in a foreign trading currency. In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communicate such adjustments in a suitable manner.
4 Trading interruption
The Exchange shall extend the auction time at opening (Delayed Auction) once by 15 minutes if the calculated auction price differs by 1% or more from the reference price or if not all unlimited orders can be executed. Continuous trading shall be interrupted for 15 minutes if the potential subsequent price differs a) by 1.0% or more from the reference price; b) by 1.0% or more from a reference price valid within 10 seconds (Avalanche Stop). For bonds with a maturity of more than 15 years, in the event of Delayed Auction, the bandwidth shall be 3% or more, in accordance with the letters a and b above. The Exchange shall open trading after a trading interruption with a random end within 30 seconds. In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communicate such adjustments in a suitable manner.
5 Price steps
The valid price steps shall be 0.01% regardless of the order price.
6 Market making and liquidity providers
6.1 Market making
The Exchange does not organise any market making.
6.2 Liquidity providers
The Exchange may define liquidity requirements and admit liquidity providers. Liquidity providers undertake to comply with the conditions set out in the "List of Charges under the Trading Rules".
7 Clearing and settlement
Trades are cleared and settled via a central counterparty. The provisions of Clause 17 Trading Rules shall apply. The counterparty shall be disclosed.
8 Deadline for reporting off-order-book trades
If a trade is executed on-exchange, off-order-book during continuous trading, the report shall be made immediately, but no later than 15 minutes after the trade has been effected. Trades executed off-order-book outside of continuous trading shall be reported before the opening of trading on the next trading day at the latest.
9 Delayed publication of off-order-book trades
The Exchange may publish trades in illiquid securities and large-volume trades with a delay. The participant may demand delayed publication from the Exchange. The provisions on delayed publication pursuant to Annex C "Trading" Directive otherwise apply. Delayed publication will take place at 07:00 CET on the trading day following the trade.
Annex N – Bonds - CHF Swiss Pfandbriefe
1 Trading periods and times
The trading periods and times shall be set as follows: a) pre-opening from 06:00 to 08:30 (CET); b) opening from 08:30 (CET) with random opening within 2 minutes; c) continuous trading from opening until 17:00 (CET); d) close of trading without closing auction; e) post-trading from close of trading until 22:00 (CET).
2 Market model, order types and trading services
The rules of the Central Limit Order Book market model shall apply for on-exchange, on-order-book trading. Normal orders, Iceberg orders and quotes are supported. The Routing Instructions "SWMB" and "SWMX" are not supported. The SwissAtMid and Swiss EBBO trading services are not supported. The Quote on Demand trading service is supported pursuant to Annex U. Self Match Prevention is not supported.
3 Order values
The price collar factor is 9. The maximum order value is CHF 50,000,000, or the equivalent amount for securities which are traded in a foreign trading currency. In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communicate such adjustments in a suitable manner.
4 Trading interruption
The Exchange shall extend the auction time at opening (Delayed Auction) once by 15 minutes if the calculated auction price differs by 1% or more from the reference price or if not all unlimited orders can be executed. Continuous trading shall be interrupted for 15 minutes if the potential closing price differs a) by 1.0% or more from the reference price; b) by 1.0% or more from a reference price valid within 10 seconds (Avalanche Stop). For bonds with a maturity of more than 15 years, in the event of Delayed Auction, the bandwidth shall be 3% or more, in accordance with the letters a and b above. The Exchange shall open trading after a trading interruption with a random end within 30 seconds. In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communicate such adjustments in a suitable manner.
5 Price steps
The valid price steps shall be 0.01% regardless of the order price.
6 Market making and liquidity providers
6.1 Market making
The Exchange does not organise any market making.
6.2 Liquidity providers
The Exchange may define liquidity requirements and admit liquidity providers. Liquidity providers undertake to comply with the conditions set out in the "List of Charges under the Trading Rules".
7 Clearing and settlement
Trades are cleared and settled via a central counterparty. The provisions of Clause 17 Trading Rules shall apply. The counterparty shall be disclosed.
8 Deadline for reporting off-order-book trades
If a trade is executed on-exchange, off-order-book during continuous trading, the report shall be made immediately, but no later than 15 minutes after the trade has been effected. Trades executed off-order-book outside of continuous trading shall be reported before the opening of trading on the next trading day at the latest.
9 Delayed publication of off-order-book trades
The Exchange may publish trades in illiquid securities and large-volume trades with a delay. The participant may demand delayed publication from the Exchange. The provisions on delayed publication pursuant to Annex C "Trading" Directive otherwise apply. Delayed publication will take place at 07:00 CET on the trading day following the trade.
Annex O – Bonds – CHF Including convertible bonds, irrespective of the trading currency, that are listed in connection with the Directive on the Listing of Special Purpose Acquisition Companies (SPACs).
1 Trading periods and times
The trading periods and times shall be set as follows: a) pre-opening from 06:00 to 09:30 (CET); b) opening from 09:30 (CET) with random opening within 2 minutes; c) continuous trading from opening until 17:00 (CET); d) close of trading without closing auction; e) post-trading from close of trading until 22:00 (CET).
2 Market model, order types and trading services
The rules of the Central Limit Order Book market model shall apply. Normal orders, Iceberg orders and quotes are supported for on-exchange, on-order-book trading. The Routing Instructions "SWMB" and "SWMX" are not supported. The SwissAtMid and Swiss EBBO trading services are not supported. The Quote on Demand trading service is supported pursuant to Annex U. Self Match Prevention is not supported.
3 Order values
The price collar factor is 9. The maximum order value is CHF 50,000,000, or the equivalent amount for securities which are traded in a foreign trading currency. In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communicate such adjustments in a suitable manner.
4 Trading interruption
The Exchange shall extend the auction time at opening (Delayed Auction) once by 15 minutes if the calculated auction price differs by 2% or more from the reference price or if not all unlimited orders can be executed. Continuous trading shall be interrupted for 15 minutes if the potential closing price differs a) by 2.0% or more from the reference price; b) by 2.0% or more from a reference price valid within 10 seconds (Avalanche Stop). For bonds with a maturity of more than 15 years, in the event of delayed opening (Delayed Auction) the bandwidth shall be 3% or more, in accordance with the letters a and b above. For volatile securities as well as delisted bonds, the delay in the opening or the trading interruption shall be 5 minutes and the bandwidth shall be 10% or more in accordance with letters a and b above.
The allocation of securities into the category of volatile securities is carried out by market control, taking into account the relevant market conditions such as liquidity and trading range. For convertible and warrant bonds continuous trading shall be interrupted if trading in the underlying is interrupted. The Exchange shall open trading after a trading interruption with a random end within 30 seconds. In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communicate such adjustments in a suitable manner.
5 Price steps
For securities with a term of a) 18 months or more, the price steps shall be 0.05%, regardless of the order price; b) less than 18 months, the price steps shall be 0.01%, regardless of the order price.
6 Market making and liquidity providers
6.1 Market making
The Exchange does not organise any market making.
6.2 Liquidity providers
The Exchange may define liquidity requirements and admit liquidity providers. Liquidity providers undertake to comply with the conditions set out in the "List of Charges under the Trading Rules".
7 Clearing and settlement
Trades are cleared and settled via a central counterparty. The provisions of Clause 17 Trading Rules shall apply. The provisions of Clause 16 Trading Rules apply to trades in convertible bonds that are listed in connection with the Directive on the Listing of Special Purpose Acquisition Companies (SPACs) and that cannot be cleared and settled via a central counterparty. The counterparty shall be disclosed.
8 Deadline for reporting off-order-book trades
If a trade is executed on-exchange, off-order-book during continuous trading, the report shall be made immediately, but no later than 15 minutes after the trade has been effected. Trades executed off-order-book outside of continuous trading shall be reported before the opening of trading on the next trading day at the latest.
9 Delayed publication of off-order-book trades
The Exchange may publish trades in illiquid securities and large-volume trades with a delay. The participant may demand delayed publication from the Exchange. The provisions on delayed publication pursuant to Annex C "Trading" Directive otherwise apply. Delayed publication will take place at 07:00 CET on the trading day following the trade.
Annex P – Bonds - Non CHF
1 Trading periods and times
The trading periods and times shall be set as follows: a) pre-opening from 06:00 to 08:30 (CET); b) opening from 08:30 (CET) with random opening within 2 minutes; c) continuous trading from opening until 17:00 (CET); d) close of trading without closing auction; e) post-trading from close of trading until 22:00 (CET).
2 Market model, order types and trading services
The rules of the Quote Driven Market market model shall apply for on-exchange, on-order-book trading. Normal orders and quotes are supported. The Routing Instructions "SWMB" and "SWMX" are not supported. The SwissAtMid and Swiss EBBO trading services are not supported. The Quote on Demand trading service is not supported. Self Match Prevention is not supported.
3 Order values
The price collar factor is 9. The maximum order value is CHF 50,000,000, or the equivalent amount for securities which are traded in a foreign trading currency. In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communicate such adjustments in a suitable manner.
4 Trading interruption
The Exchange shall extend the auction time at opening (Delayed Auction) once by a maximum of 5 minutes if there is no quote in the order book at the time of possible execution or if not all unlimited orders can be executed. Continuous trading shall be interrupted if there is no quote in the order book at the time of possible execution. Trading shall be immediately resumed as soon as a quote is entered, but no later than after 5 minutes. The Exchange shall open trading after a trading interruption with a random end within 30 seconds. In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communicate such adjustments in a suitable manner.
5 Price steps
The price steps shall be 0.01%, regardless of the order price.
6 Market making and liquidity providers
6.1 Market making
The Exchange does not organise any market making.
6.2 Liquidity providers
The Exchange may define liquidity requirements and admit liquidity providers. Liquidity providers undertake to comply with the conditions set out in the "List of Charges under the Trading Rules".
7 Clearing and settlement
Trades are not cleared and settled via a central counterparty. The provisions of Clause 16 Trading Rules shall apply. The counterparty shall be disclosed.
8 Deadline for reporting off-order-book trades
If a trade is executed on-exchange, off-order-book during continuous trading, the report shall be made immediately, but no later than 15 minutes after the trade has been effected. Trades executed off-order-book outside of continuous trading shall be reported before the opening of trading on the next trading day at the latest.
9 Delayed publication of off-order-book trades
The Exchange may publish trades in illiquid securities and large-volume trades with a delay. The participant may demand delayed publication from the Exchange. The provisions on delayed publication pursuant to Annex C "Trading" Directive otherwise apply. Delayed publication will take place at 19:00 CET two trading days following the trade.
Annex Q – Structured Products
1 Trading periods and times
The trading periods and times shall be set as follows: a) pre-opening from 06:00 to 09:15 (CET); b) opening from 09:15 (CET) with random opening within 2 minutes; c) continuous trading from opening until 17:15 (CET); Structured Products on Bonds of the Swiss Confederation close at 17:00 (CET); d) close of trading without closing auction; e) post-trading from close of trading until 22:00 (CET).
2 Market model, order types and trading services
The rules of the Price Validation Market market model shall apply for on-exchange, on-order-book trading. Normal orders, Retail orders and quotes are supported. The Routing Instructions "SWMB" and "SWMX" are not supported. The SwissAtMid and Swiss EBBO trading services are not supported. The Quote on Demand trading service is not supported. Self Match Prevention is not supported.
3 Order values
The price collar factor is 99. The maximum order value is CHF 10,000,000, or the equivalent amount for securities which are traded in a foreign trading currency. In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communicate such adjustments in a suitable manner.
4 Trading interruption
The Exchange shall extend the auction time at opening (Delayed Auction) once by a maximum of 30 seconds if there is no quote in the order book at the time of possible execution or if not all unlimited orders can be executed. Continuous trading shall be interrupted if there is no quote in the order book at the time of possible execution. Trading shall be immediately resumed as soon as a quote is entered, but no later than after 30 seconds. The Exchange interrupts continuous trading (Price Validation Phase) if there is a possible execution between an order and a quote. Trading shall resume immediately as soon as a) the quote is confirmed or amended; or b) during the duration of the price validation phase, the quote or order that would have led to a possible execution has been deleted or changed so that no execution can take place during the auction; however, after 1 second at the latest.
The Exchange may interrupt trading if trading in the underlying is interrupted. Trading is interrupted only if the Structured Product is based on one single underlying with its primary listing on SIX Swiss Exchange AG. The Exchange shall open trading after a trading interruption (outside of the Price Validation Phase) with a random end within 5 seconds. In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communicate such adjustments in a suitable manner.
5 Price steps
5.1 Warrants, Structured Products Warrants & Certificates
The valid price steps shall be 0.001 of the relevant trading currency regardless of the order price. The valid price steps for securities with a reference price of CHF 10,000 or above of the relevant trading currency shall be 1.00 regardless of the order price.
5.2 Structured Products Bonds
The valid price steps shall be 0.01% regardless of the order price.
6 Market making and liquidity providers
6.1 Market making
The Exchange shall organise market making and admit market makers. The market maker contractually undertakes to meet the following requirements over 90% (on a monthly basis) of the official trading times for Alternative Investments, Actively Managed Certificates (AMC), Floored Floaters, Constant Proportion Portfolio Insurance (CPPI) and Credit Default Warrants (CDW):
6.1.1 Certificates on Alternative Investments
The maximum trading spread between the bid and ask prices is no more than 3%. The minimum volume on both the bid or ask side is CHF 50,000.
6.1.2 Actively Managed Certificates (AMC)
The maximum trading spread between the bid and ask prices is no more than 3%. The minimum volume on both the bid or ask side is CHF 50,000.
6.1.3 Floored Floaters
The maximum trading spread between the bid and ask prices is no more than 3%. The minimum volume on both the bid or ask side is CHF 50,000.
6.1.4 Constant Proportion Portfolio Insurance (CPPI)
The maximum trading spread between the bid and ask prices is no more than 3%. The minimum volume on both the bid or ask side is CHF 50,000.
6.1.5 Credit Default Warrants (CDW)
The maximum trading spread between the bid and ask prices is no more than 3%. The minimum volume on both the bid or ask side is CHF 50,000.
6.2 Liquidity providers
The Exchange may define liquidity requirements and admit liquidity providers. Liquidity providers undertake to comply with the conditions set out in the "List of Charges under the Trading Rules".
7 Clearing and settlement
Trades are not cleared and settled via a central counterparty. The provisions of Clause 16 Trading Rules shall apply. The counterparty shall be disclosed.
8 Deadline for reporting off-order-book trades
If a trade is executed on-exchange, off-order-book during continuous trading, the report shall be made immediately, but no later than 3 minutes after the trade has been effected. Trades at a future net asset value are deemed to be effected in accordance with paragraph 1 as soon as the net asset value on which the trade is based is known. The trades are to be reported with the trade type “NAV Trade” (Annex B “Trading” directive). Trades executed off-order-book outside of continuous trading shall be reported before the opening of trading on the next trading day at the latest.
9 Delayed publication of off-order-book trades
The delayed publication function is not available.
Annex R – Structured Products ETH (Extended Trading Hours)
1 Trading periods and times
The trading periods and times shall be set as follows: a) pre-opening from 6:00 to 8:00 (CET); b) opening from 8:00 (CET) with random opening within 2 minutes; c) continuous trading from opening until 21:45 (CET); d) close of trading without closing auction; e) post-trading from close of trading until 22:00 (CET).
2 Market model, order types and trading services
The rules of the Price Validation Market market model shall apply for on-exchange, on-order-book trading. Normal orders, Retail orders and quotes are supported. The Routing Instructions “SWMB” and “SWMX” are not supported. The SwissAtMid and Swiss EBBO trading services are not supported. The Quote on Demand trading service is not supported. Self Match Prevention is not supported.
3 Order values
The price collar factor is 99. The maximum order value is CHF 10,000,000, or the equivalent amount for securities which are traded in a foreign trading currency. In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communicate such adjustments in a suitable manner.
4 Trading interruption
The Exchange shall extend the auction time at opening (Delayed Auction) once by a maximum of 30 seconds if there is no quote in the order book at the time of possible execution or if not all unlimited orders can be executed. Continuous trading shall be interrupted if there is no quote in the order book at the time of possible execution. Trading shall be immediately resumed as soon as a quote is entered, but no later than after 30 seconds. The Exchange interrupts continuous trading (Price Validation Phase) if there is a possible execution between an order and a quote. Trading shall resume immediately as soon as a) the quote is confirmed or amended; or b) during the duration of the price validation phase, the quote or order that would have led to a possible execution has been deleted or changed so that no execution can take place during the auction; however, after 1 second at the latest. The Exchange may interrupt trading if trading in the underlying is interrupted. Trading is interrupted only if the Structured Product is based on one single underlying with its primary listing on SIX Swiss Exchange AG.
The Exchange shall open trading after a trading interruption (outside of the Price Validation Phase) with a random end within 5 seconds. In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communicate such adjustments in a suitable manner.
5 Price steps
5.1 Warrants, Structured Products Warrants & Certificates
The valid price steps shall be 0.001 of the relevant trading currency regardless of the order price. The valid price steps for securities with a reference price of CHF 10,000 or above of the relevant trading currency shall be 1.00 regardless of the order price.
5.2 Structured Products Bonds
The valid price steps shall be 0.01% of the relevant trading currency regardless of the limit.
6 Market making and liquidity providers
6.1 Market making
The Exchange shall organise market making and admit market makers. The market maker contractually undertakes to meet the following requirements over 90% (on a monthly basis) of the official trading times for Alternative Investments, Actively Managed Certificates (AMC), Floored Floaters, Constant Proportion Portfolio Insurance (CPPI) and Credit Default Warrants (CDW):
6.1.1 Certificates on Alternative Investments
The maximum trading spread between the bid and ask prices is no more than 3%. The minimum volume on both the bid and ask side is CHF 50,000.
6.1.2 Actively Managed Certificates (AMC)
The maximum trading spread between the bid and ask prices is no more than 3%. The minimum volume on both the bid and ask side is CHF 50,000.
6.1.3 Floored Floaters
The maximum trading spread between the bid and ask prices is no more than 3%. The minimum volume on both the bid and ask side is CHF 50,000.
6.1.4 Constant Proportion Portfolio Insurance (CPPI)
The maximum trading spread between the bid and ask prices is no more than 3%. The minimum volume on both the bid and ask side is CHF 50,000.
6.1.5 Credit Default Warrants (CDW)
The maximum trading spread between the bid and ask prices is no more than 3%. The minimum volume on both the bid and ask side is CHF 50,000.
6.2 Liquidity providers
The Exchange may define liquidity requirements and admit liquidity providers. Liquidity providers undertake to comply with the conditions set out in the “List of Charges under the Trading Rules”.
7 Clearing and settlement
Trades are not cleared and settled via a central counterparty. The provisions of Clause 16 Trading Rules shall apply. The counterparty shall be disclosed.
8 Deadline for reporting off-order-book trades
If a trade is executed on-exchange, off-order-book during continuous trading, the report shall be made immediately, but no later than 3 minutes after the trade has been effected. Trades at a future net asset value are deemed to be effected in accordance with para. 1 as soon as the net asset value on which the trade is based is known. Trades are to be reported with the “NAV Trade” trade type (Annex B “Trading” directive). Trades executed off-order-book outside of continuous trading shall be reported before the opening of trading on the next trading day at the latest.
9 Delayed publication of off-order-book trades
The delayed publication function is not available.
10 Transfer Between Trading Segments
Instruments transferred from the trading segment «Structured Products ETH (Extended Trading Hours)» to the trading segment «Structured Products» may not be transferred back to the trading segment «Structured Products ETH (Extended Trading Hours)» for a period of four weeks.
Annex S – Exchange Traded Products (ETP)
1 Trading periods and times
The trading periods and times shall be set as follows: a) pre-opening from 06:00 to 09:00 (CET); b) opening from 09:00 (CET) with random opening within 2 minutes; c) continuous trading from opening until 17:30 (CET); d) closing auction from 17:30 to 17:35 (CET) with random close of trading within 2 minutes; e) post-trading from close of trading until 22:00 (CET).
2 Market model, order types and trading services
The rules of the Quote Driven Market market model shall apply for on-exchange, on-order-book trading. Normal orders, Iceberg orders, Retail orders and quotes are supported. The Routing Instructions "SWMB" and "SWMX" are not supported. The SwissAtMid and Swiss EBBO trading services are not supported. The Quote on Demand trading service is supported. The default value for the maximum duration of the trading modes for Quote on Demand is determined as follows: a) “Discretion only” lasts 5 minutes maximum; b) “Auto-Execute or Cancel” lasts a maximum of 1 second with random execution if the conditions for execution are met; c) “Auto-Execute and Optional Discretion” lasts 1 second maximum with random execution if the conditions for execution are met and if no execution occurs, an additional 5 minutes maximum. The standard value for the minimum number of responding liquidity providers for automatic execution (“Auto-Execute”) is 1. The participant may individually select a maximum of 10 Quote on Demand registered liquidity providers for a quote request. The participant identification (Party ID) of the participant for quote requests is disclosed to the liquidity providers. The designation of the transaction type (buy/sell) of the quote requests is not disclosed to the liquidity providers. Self Match Prevention is supported for the Quote Driven Market. Self Match Prevention is not supported for Quote on Demand.
3 Order values
The price collar factor is generally 9. The maximum order value is: a) CHF 10,000,000, or the equivalent amount for securities which are traded in a foreign trading currency for Quote Driven Market; b) CHF 250,000,000, or the equivalent amount for securities which are traded in a foreign trading currency for Quote on Demand. The price deviation of quote requests to the current price in the Quote Driven Market (QDM) is 10% or more. In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communicate such adjustments in a suitable manner.
4 Trading interruption
The Exchange shall extend the auction time at opening (Delayed Auction) once by a maximum of 5 minutes if there is no quote in the order book at the time of possible execution or if not all unlimited orders can be executed. Continuous trading shall be interrupted if there is no quote in the order book at the time of possible execution. Trading shall be immediately resumed as soon as a quote is entered, but no later than after 5 minutes. The Exchange shall extend the auction time in the closing auction (Delayed Auction) once by a maximum of 2 minutes if there is no quote in the order book at the time of possible execution or if not all unlimited orders can be executed. The Exchange shall open trading after a trading interruption with a random end within 30 seconds. In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communicate such adjustments in a suitable manner.
5 Price steps
5.1 Quote Driven Market
The price steps laid down in Liquidity Band F of Annex D of the “Trading” Directive apply in principle to the Quote Driven Market. The valid price steps for securities in the money market products and fixed income investment category are defined as follows depending on the order price (details in trading currency):
From | To | Price steps | |
|---|---|---|---|
a) | 0.01 | 4.9999 | 0.0001 |
b) | 5 | 9.9998 | 0.0002 |
c) | 10 | 19.9995 | 0.0005 |
d) | 20 | 49.999 | 0.001 |
e) | 50 | 99.998 | 0.002 |
f) | 100 | 199.995 | 0.005 |
g) | 200 | 499.99 | 0.01 |
h) | 500 | 999.98 | 0.02 |
i) | 1,000 | 1,999.95 | 0.05 |
j) | 2,000 | 4,999.90 | 0.1 |
k) | 5,000 | 9,999.80 | 0.2 |
l) | 10,000 | 19,999.50 | 0.5 |
m) | 20,000 | 49,999 | 1 |
n) | 50,000 | and over | 2 |
The valid price steps for securities with a reference price of 100,000 or above in the relevant trading currency shall be 10.00 regardless of the order price and investment category.
5.2 Quote on Demand
For the trading service Quote on Demand, the valid price step is 0.0001 regardless of the order price. The valid price steps for securities with Japanese Yen (JPY) as their trading currency shall be 1.00 regardless of the order price.
6 Market making and liquidity providers
6.1 Market making
6.1.1 Quote Driven Market
The Exchange shall organise market making and admit market makers. The market maker contractually undertakes to meet the following requirements over 90% (on a monthly basis) of the official trading times: a) If trading on the domestic market of at least 50% of underlyings has been opened, or a functioning OTC market exists, the market maker shall provide bid and ask prices with a maximum trading spread of 2%; or b) If trading on the domestic market of at least 50% of underlyings has not been opened, or no functioning OTC market exists, the market maker shall provide bid and ask prices with a maximum trading spread of 5%. The minimum volume on both the bid and ask sides is EUR 50,000.
6.1.2 Quote on Demand
The Exchange does not organise any market making.
6.2 Liquidity providers
6.2.1 Quote Driven Market
The Exchange does not admit any liquidity providers.
6.2.2 Quote on Demand
The Exchange may define liquidity requirements and admit liquidity providers. Liquidity providers undertake to comply with the conditions set out in the “List of Charges under the Trading Rules”.
7 Clearing and settlement
Trades are cleared and settled via a central counterparty where possible. The provisions of Clause 17 Trading Rules shall apply. The provisions of Clause 16 Trading Rules apply to trades in securities that cannot be cleared and settled via a central counterparty. The valid settlement provisions are defined by the Exchange per security and published together with the static data. The counterparty shall be disclosed.
8 Deadline for reporting off-order-book trades
If a trade is executed on-exchange, off-order-book during continuous trading, the report shall be made immediately, but no later than 3 minutes after the trade has been effected. Trades at a future net asset value are deemed to be effected in accordance with paragraph 1 as soon as the net asset value on which the trade is based is known. The trades are to be reported with the trade type “NAV Trade” (Annex B “Trading” directive).
Trades executed off-order-book outside of continuous trading shall be reported before the opening of trading on the next trading day at the latest.
9 Delayed publication of trades
9.1 Trades in the Quote Driven Market and off-order-book
The delayed publication function is not available.
9.2 Trades in the Quote on Demand trade service
The Exchange may publish trades with the required minimum order size on a delayed basis compared with normal market size. The provisions on delayed publication pursuant to Clause 11.14 of the “Alternative Trading” directive apply.
Annex T – ETF/ETP QOD Europe
1 Trading periods and times
The trading periods and times shall be set as follows: a) pre-opening from 06:00 to 09:00 (CET); b) start of trading without opening auction from 09:00 (CET); c) continuous trading from start of trading until 17:30 (CET); d) close of trading without closing auction; e) post-trading from close of trading until 22:00 (CET).
2 Market model, order types and trading services
Quote requests and quotes are supported. The Routing Instruction “QODN” is supported. The Routing Instruction “QODS” is not supported. The Quote on Demand trading service is supported. The default value for the maximum trading mode duration for Quote on Demand is determined as follows: a) “Discretion only” lasts 5 minutes maximum; b) “Auto-Execute or Cancel” lasts 1 second maximum with random execution if the conditions for execution are met; c) “Auto-Execute and Optional Discretion” lasts 1 second maximum with random execution if the conditions for execution are met and if no execution occurs, an additional 5 minutes maximum. The standard value for the minimum number of responding liquidity providers for automatic execution (“Auto-Execute”) is 1. The participant may individually select a maximum of 10 Quote on Demand registered liquidity providers for a quote request. The participant identification (Party ID) of the participant for quote requests is disclosed to the liquidity providers. The designation of the transaction type (buy/sell) of the quote requests is not disclosed to the liquidity providers. Self Match Prevention is not supported.
3 Order values
The price collar factor is generally 9. The maximum order value is CHF 250,000,000, or the equivalent amount for securities which are traded in a foreign trading currency. The price deviation of quote requests to the current reference price is 50% or more. In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communicate such adjustments in a suitable manner.
4 Trading interruption
Trading shall not be interrupted.
5 Price steps
The valid price step is 0.0001 regardless of the order price. The valid price steps for securities with Japanese Yen (JPY) as their trading currency shall be 1.00 regardless of the order price.
6 Market making and liquidity providers
6.1 Market making
The Exchange does not organise any market making.
6.2 Liquidity providers
The Exchange may define liquidity requirements and admit liquidity providers. Liquidity providers undertake to comply with the conditions set out in the “List of Charges under the Trading Rules”.
7 Clearing and settlement
Trades have to be cleared and settled via a central counterparty. The provisions of Clause 17 Trading Rules shall apply. The valid settlement provisions are defined by the Exchange per security and published together with the static data. The counterparty shall be disclosed.
8 Deadline for reporting off-order-book trades
If a trade is executed on-exchange, off-order-book during continuous trading, the report shall be made immediately, but no later than 3 minutes after the trade has been effected. As defined in paragraph 1, trades at a future net asset value are considered to be made as soon as the trade’s underlying net asset value is known. The trades are to be reported with the “NAV Trade” trade type (Annex B “Trading” directive). Trades executed off-order-book outside of continuous trading shall be reported before the opening of trading on the next trading day at the latest.
9 Delayed publication of trades
The Exchange may publish trades with the required minimum order size on a delayed basis compared with normal market size. The provisions on delayed publication pursuant to Clause 11.14 of the “Alternative Trading” directive apply.
Annex U – QOD CHF-Bonds
1 Trading periods and times
The trading periods and times shall be set as follows: a) pre-opening from 06:00 to 09:30 (CET) (until 08:30 (CET) for bonds of the Swiss Confederation and Swiss Pfandbriefe); b) start of trading without opening auction from 09:30 (CET) (from 08:30 (CET) for bonds of the Swiss Confederation and Swiss Pfandbriefe); c) continuous trading from start of trading until 17:00 (CET); d) close of trading without closing auction; e) post-trading from close of trading until 22:00 (CET).
2 Market model, order types and trading services
Quote requests and quotes are supported. The Routing Instruction “QODN” is supported. The Routing Instruction “QODS” is not supported. Quote on Demand is supported. The default value for the maximum trading mode duration for Quote on Demand is determined as follows: a) “Discretion only” lasts 5 minutes maximum; b) “Auto-Execute or Cancel” lasts 60 seconds maximum with random execution if the conditions for execution are met; c) “Auto-Execute and Optional Discretion” lasts 60 seconds maximum with random execution if the conditions for execution are met and if no execution occurs, an additional 5 minutes maximum. The standard value for the minimum number of responding liquidity providers for automatic execution (“Auto-Execute”) is 1. The participant may individually select a maximum of 10 Quote on Demand registered liquidity providers for a quote request. The participant identification (Party ID) of the participant and the designation of the transaction type (buy/sell) of the quote requests are disclosed to the liquidity providers. Self Match Prevention is not supported.
3 Order values
The price collar factor is generally 9. The maximum order value is CHF 250,000,000, or the equivalent amount for securities which are traded in a foreign trading currency. The price deviation of quote requests to the current reference price is 10% or more. In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communicate such adjustments in a suitable manner.
4 Trading interruption
Trading shall not be interrupted.
5 Price steps
The valid price step is 0.01% regardless of the order price.
6 Market making and liquidity providers
6.1 Market making
The Exchange does not organise any market making.
6.2 Liquidity providers
The Exchange may define liquidity requirements and admit liquidity providers. Liquidity providers undertake to comply with any conditions set out in the “List of Charges under the Trading Rules”.
7 Clearing and settlement
Trades have to be cleared and settled via a central counterparty. The provisions of Clause 17 Trading Rules shall apply. The provisions of Clause 16 Trading Rules apply to trades in convertible bonds that are listed in connection with the Directive on the Listing of Special Purpose Acquisition Companies (SPACs) and that cannot be cleared and settled via a central counterparty. The counterparty shall be disclosed.
8 Deadline for reporting off-order-book trades
If a trade is executed on-exchange, off-order-book during continuous trading, the report shall be made immediately, but no later than 15 minutes after the trade has been effected. Trades executed off-order-book outside of continuous trading shall be reported before the opening of trading on the next trading day at the latest.
9 Delayed publication of trades
The Exchange may publish trades in illiquid securities and large-volume trades with a delay. The provisions on delayed publication pursuant to Clause 13.10 of the “Alternative Trading” directive apply.
Annex G – Rights and Options
1 | Trading periods and times | |
The trading periods and times shall be set as follows: | ||
a) pre-opening from 06:00 to 09:15 (CET); | ||
b) opening from 09:15 (CET) with random opening within 2 minutes; | ||
c) continuous trading from opening until 17:15 (CET); | ||
d) close of trading without closing auction; | ||
e) post-trading from close of trading until 22:00 (CET). | ||
2 | Market model, order types and trading services | |
The rules of the Central Limit Order Book market model shall apply for on-exchange, on-order-book trad- | ||
ing. | ||
Normal orders and Retail orders are supported. | ||
The Routing Instructions "SWMB" and "SWMX" are not supported. | ||
The SwissAtMid and Swiss EBBO trading services are not supported. | ||
The Quote on Demand trading service is not supported. | ||
Self Match Prevention is not supported. | ||
3 | Order values | |
The price collar factor is 99. | ||
The maximum order value is CHF 10,000,000, or the equivalent amount for securities which are traded in | ||
a foreign trading currency. | ||
In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communi- | ||
cate such adjustments in a suitable manner. | ||
4 | Trading interruption | |
Continuous trading shall be interrupted if trade in the underlying is interrupted. | ||
5 | Price steps | |
Securities are allocated to price steps on the basis of the price steps for the corresponding underlying se- | ||
curity. | ||
6 | Market making and liquidity providers | |
6.1 | Market making | |
The Exchange does not organise any market making. | ||
6.2 | Liquidity providers | |
The Exchange does not admit any liquidity providers. |
Annex H – Separate Trading Lines
1 | Trading periods and times | |
The trading periods and times shall be set as follows: | ||
a) pre-opening from 06:00 to 09:00 (CET); | ||
b) opening from 09:00 (CET) with random opening within 2 minutes; | ||
c) continuous trading from opening until 17:20 (CET); | ||
d) closing auction from 17:20 to 17:30 (CET) with random close of trading within 2 minutes; | ||
e) post-trading from close of trading until 22:00 (CET). | ||
2 | Market model, order types and trading services | |
The rules of the Central Limit Order Book market model shall apply for on-exchange, on-order-book trad- | ||
ing. | ||
Normal orders and Retail orders are supported. | ||
The Routing Instructions "SWMB" and "SWMX" are not supported. | ||
The SwissAtMid and Swiss EBBO trading services are not supported. | ||
The Quote on Demand trading service is not supported. | ||
Self Match Prevention is not supported. | ||
3 | Order values | |
The price collar factor is 9. | ||
The maximum order value is CHF 10,000,000, or the equivalent amount for securities which are traded in | ||
a foreign trading currency. | ||
In certain cases, the Exchange may adjust these parameters at short notice. The Exchange shall communi- | ||
cate such adjustments in a suitable manner. | ||
4 | Trading interruption | |
Continuous trading shall be interrupted if trading in the underlying is interrupted. | ||
5 | Price steps | |
The price steps laid down in Annex D of the "Trading" Directive apply. | ||
Securities are allocated to price steps on the basis of the price steps for the corresponding first trading | ||
line. | ||
6 | Market making and liquidity providers | |
6.1 | Market making | |
The Exchange does not organise any market making. | ||
6.2 | Liquidity providers | |
The Exchange does not admit any liquidity providers. |